

myFICO - Credit Score Tracking analysis by Appwee
Credit tracking apps often feel useful the first time you open them, then quietly disappear from your phone once the initial curiosity wears off. I approached myFICO with that problem in mind: can it become a practical part of a financial routine, or is it mainly a quick look at a number? After spending time with this finance app from FICO, I found that its strongest value comes from connecting a credit score with the Equifax report behind it. That makes it more useful than a simple score display, although it still demands a sensible schedule so checking does not become a source of unnecessary worry.
The app is free, aimed at Everyone, and has built a substantial audience with more than a million installs. Its average rating sits at 4.3 from roughly twelve thousand ratings, with about four and a half thousand written reviews. Those figures suggest a product that is familiar to many Android users, but they do not automatically make it right for every borrower. Credit information is personal, and the best experience depends on whether you want to understand your borrowing position rather than merely watch a number move.
From first-week curiosity to a useful credit routine
What makes the first session worthwhile
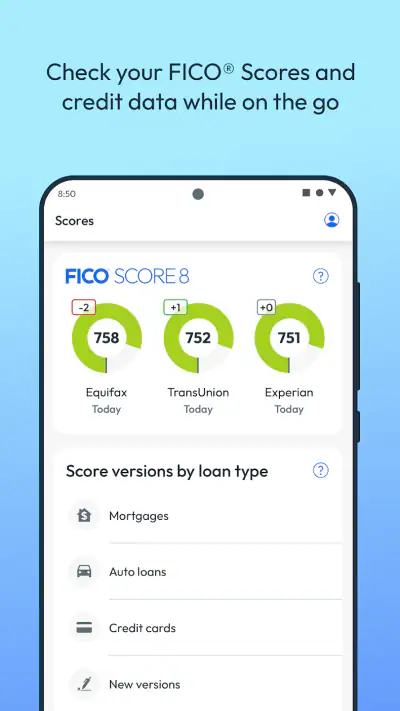
The first appeal is straightforward. myFICO puts a FICO Score and an Equifax credit report in the same financial app, giving me a more meaningful starting point than a standalone score widget. A score without context can be hard to interpret: a lower result may be connected to balances, payment history, account age, or something that needs checking in the report. Seeing the score alongside report information encourages a better question: what is influencing this result?
That distinction matters when you are preparing for a major application. If I were considering a mortgage, a vehicle loan, or a new credit card, I would rather review my credit position before submitting an application than discover a problem after a lender has already assessed me. The app is especially helpful as a preparation tool because it gives the review process a defined purpose. I can look for unfamiliar accounts, check whether reported balances make sense, and decide whether I need to pause before applying.
The app is not just for people with excellent credit. Someone rebuilding credit may use it to understand whether steady payments and lower balances are moving in the right direction. Someone with a long credit history may use it as a second set of eyes when an account or inquiry looks unfamiliar. In both cases, the report is more valuable than the score alone because it gives the user something to investigate rather than simply something to admire or fear.
A realistic first-week workflow
My preferred way to begin is not to open the app repeatedly. I would first review the score, then move through the Equifax report slowly, separating items I recognize from anything that deserves a closer look. I would note the date of the review and avoid making a financial decision based on one isolated glance. This approach turns the first week into an orientation period instead of a hunt for instant improvement.
One practical scenario is a person planning to apply for a mortgage in several months. During the first session, the app can help establish a baseline and reveal whether the report contains outdated or unfamiliar information. The useful action is not immediately applying for another product; it is creating enough time to understand what is already recorded. If something appears wrong, the user can investigate through the appropriate channels before a major lender review.
Another scenario involves a credit card user who has recently paid down a balance. The app can help that person keep expectations realistic. A payment does not necessarily mean the score will change immediately, and a score is not a live reflection of every transaction. Treating the app as a progress journal rather than a real-time scoreboard prevents a lot of frustration.
What the app does better than a basic score tracker
Compared with a banking app that shows only a credit estimate, myFICO has a more focused purpose. Its connection between the FICO Score and Equifax report gives the user a clearer path from observation to investigation. A general budgeting app may be better for spending categories, cash-flow planning, or bill reminders, but those are not the central job here. This app earns its place when the question is specifically about credit standing and the information supporting it.
That focus is also a limitation. If I wanted one dashboard for savings goals, subscriptions, debt payoff, and monthly spending, I would choose a broader personal-finance tool. myFICO should complement that kind of app, not replace it. Its first-week appeal is strongest for a defined credit task, such as reviewing a report before borrowing or learning how credit information is presented.
Why the report deserves more attention than the headline number
The most useful habit is to read the report whenever the score changes noticeably, rather than reacting to the number in isolation. A score can encourage a quick emotional response, while the report invites a more careful check. I would look for changes in accounts, balances, payment information, and inquiries, then ask whether each change matches something I actually did.
This is one of the app’s less obvious strengths: it can make credit monitoring more investigative. The user is not limited to asking whether the score is “good.” Instead, the user can ask whether the underlying record is accurate and whether recent financial behavior is being reflected as expected. That shift is valuable for people who are learning how credit works.
Keeping value after the novelty fades
Month-to-month usefulness depends on a schedule
After the first week, the app’s value becomes quieter. It is not an entertainment product, and there is no reason to open it every day. I would give it a place in a monthly or occasional financial review, especially around planned borrowing, a change in credit-card usage, or a period of rebuilding credit. The exact rhythm matters less than having one. Without a routine, the app can become either forgotten or overused.
A monthly check can be paired with a broader money review. I might first examine spending and upcoming bills in my usual finance tools, then use myFICO to review the credit side of that picture. This separation keeps the app’s role clear: it is for understanding the credit record, not for managing every part of household finances.
For someone preparing for a loan, a more deliberate short-term routine may make sense. I would review the report, record questions, avoid unnecessary applications, and return later to see whether the relevant information has changed. The benefit is not that the app promises a particular outcome. The benefit is that it gives me a consistent place to check what is being reported before I make an important application.
Maintenance is light, but attention is still required
The app itself is not difficult to maintain. It is free, and the current version is 4.0.23.4. It was released on August 18, 2015, and supports a minimum operating system of 12. Those details make it important to keep the device’s software situation in mind before expecting a smooth installation or update. Once installed, the larger maintenance task is personal: remembering to review information calmly and protect the privacy of what the app displays.
I would not treat a credit app like a notification-heavy social feed. Turning every possible alert into an urgent event can make ordinary reporting changes feel like emergencies. A better maintenance habit is to choose a regular review point and keep notes about questions that need follow-up. This is particularly useful when a score changes but the reason is not immediately obvious.
There is also a difference between monitoring and repairing. myFICO can help me notice information that deserves attention, but noticing a problem is not the same as correcting it. Users should be prepared to investigate unfamiliar entries through the proper reporting or creditor process rather than assuming the app itself can resolve every issue. That boundary is easy to overlook when a product presents score and report information together.
Three habits that make the app more useful
Review the report before applying for major credit. This gives me time to recognize unfamiliar information and question anything that does not fit my records.
Compare changes with real financial events. If I recently changed card usage or paid down a balance, I can use the app as a record of what eventually appears rather than expecting an instant response.
Keep a short written log of observations. Recording the date, the score, and the main report changes makes occasional reviews more useful than relying on memory.
These habits also reduce the temptation to check compulsively. The app works best when it supports a decision or a review, not when it becomes a source of constant reassurance.
Where recurring value can weaken
The recurring value is lower for someone whose credit situation is stable and who has no upcoming borrowing decision. In that case, a periodic report review may be enough, and the app may not offer a compelling reason to open it frequently. The product’s usefulness is tied to the importance of the credit questions in your life.
It may also feel limited to users who expect a complete financial coach. The app does not become a replacement for a budget, debt planner, or personal finance organizer simply because it belongs to the finance category. If your main goal is controlling daily spending, tracking bills, or building an emergency fund, another tool will likely deserve more regular attention.
Sources of fatigue and possible misunderstandings
The biggest source of fatigue is score watching. Credit scores are easy to reduce to a single personal grade, so normal movement can feel like a judgment. If I opened the app after every financial action, I would probably create more anxiety than insight. The healthier approach is to focus on patterns and report accuracy, not on winning a daily contest against a number.
Another source of friction is the gap between what a user expects and what credit reporting can show at a given moment. Financial activity may not appear immediately, and different lenders can use different scoring approaches. Because of that, the app should be treated as an informative view of the Equifax record and FICO Score it presents, not as a guarantee of the exact result a future lender will use.
This is an important trade-off when comparing myFICO with free score features inside banking apps. A bank may offer a convenient glance at a score as part of a wider account dashboard. That may be enough for casual awareness. myFICO is the better fit when the report context matters and you are willing to spend more time examining your credit information. Convenience wins in the first case; focused credit review wins in the second.
Privacy is another reason to use the app deliberately. Credit information is sensitive, so I would install it only on a device I control, use a strong device lock, and avoid discussing account details in public settings. These are ordinary precautions, but they matter more here than they would with a simple weather or shopping app. The app’s Everyone content rating describes its audience, not the sensitivity of the financial information a user may view inside it.
Who should use it and who should skip it
I would recommend myFICO to people planning a mortgage or loan, reviewing their credit before applying for a card, rebuilding after missed payments, or trying to understand why a score does not match their expectations. It is also a sensible choice for anyone who wants a dedicated place to inspect an Equifax report rather than relying solely on a score shown elsewhere.
I would skip it if my only goal were a broad household budget, automatic expense categorization, or daily bill management. I would also avoid making it a central part of my routine if checking credit numbers tends to trigger anxiety. In that situation, a scheduled review through a less frequently opened tool may be healthier, provided it still meets the person’s monitoring needs.
Users should also check the operating-system requirement before downloading. The app requires at least version 12 of the mobile operating system, so an older device may not be suitable. That is a small practical detail, but it can save time when choosing between this dedicated app and a browser-based or banking alternative.
Does it earn lasting space?
For me, the answer is yes, but conditionally. myFICO earns lasting space when I give it a specific job: review the FICO Score, examine the Equifax report, and support thoughtful decisions before borrowing. It does not earn that space by demanding daily attention, and it should not be judged as a replacement for a complete money-management suite.
The app’s long-term strength is its ability to turn credit monitoring into a repeatable review rather than a one-time novelty. Its weakness is that the experience can become repetitive or stressful if the user expects instant explanations, immediate score movement, or a full repair service. The best results come from pairing occasional checks with real financial habits outside the app.
After the first-week curiosity fades, I would keep it installed for planned credit reviews and major financial milestones. I would not open it automatically every morning. That balance captures its real value: myFICO is most useful as a calm credit-maintenance tool, not as a constant measure of financial self-worth. For readers who want focused access to a FICO Score and Equifax report, the free app from FICO is a practical choice. For readers seeking budgeting, spending control, or a complete financial command center, another app will be a better long-term home.
Gallery
myFICO - Credit Score Tracking Pros and Cons
- Shows FICO Scores used by many lenders
- Tracks score changes over time with historical data
- Provides identity theft and credit monitoring alerts
- Offers personalized insights into factors affecting your score
- Includes access to educational resources about credit management
- Full score access requires a relatively expensive subscription
- Some features vary depending on the selected membership plan
- Frequent alerts may feel overwhelming for some users
- Credit reports and scores may not update immediately
- Primarily useful in the United States credit system
myFICO - Credit Score Tracking Frequently Asked Questions
What is myFICO - Credit Score Tracking, and what does it offer?
myFICO - Credit Score Tracking is a credit-monitoring app designed to help users view and understand their FICO® Scores, credit reports, and related changes. Depending on the plan you choose, it may provide scores from different credit bureaus, score updates, credit-report access, monitoring alerts, and explanations of the factors affecting your credit. Features and update frequency can vary by subscription level.
Is myFICO free to download and use?
The app can generally be downloaded without paying an installation fee, but many of its most important features require a paid myFICO subscription or an eligible account. Free access, if available, may be limited compared with premium plans. Before subscribing, review the current pricing, billing schedule, trial terms, automatic-renewal conditions, and cancellation policy shown in the app or on the official myFICO website.
Will using myFICO affect my credit score?
Checking your own credit score or credit report through myFICO is considered a soft inquiry and does not normally lower your credit score. The app is intended for personal monitoring and education, not for applying for credit directly. However, if you use information from the app to apply for a loan, card, or other financial product, the lender may perform a separate hard inquiry that could affect your score.
How accurate and up to date are the scores and credit reports in the app?
myFICO provides information based on data received from participating credit bureaus and the scoring models included with your account. Scores may not update instantly after a lender reports new information, and different lenders can use different FICO® versions or bureau data. For that reason, the score shown in the app may differ from a lender’s score, especially around major credit applications.
Is my personal and financial information secure in myFICO?
Because myFICO handles sensitive identity and credit information, users should sign in only through the official app and keep their password, device, and verification details protected. The service uses security measures intended to safeguard account data, but no online platform can guarantee zero risk. Enable available security features, avoid sharing login codes, and contact official support promptly if you notice suspicious activity.














